By Uzair Saleem — The Changer
LAHORE: Pakistan is beginning to build a new financial safety net around smaller exporters, combining a Rs3 billion domestic risk pool with international reinsurance in an attempt to tackle one of the less visible obstacles confronting companies seeking customers abroad: the possibility that overseas buyers simply do not pay.
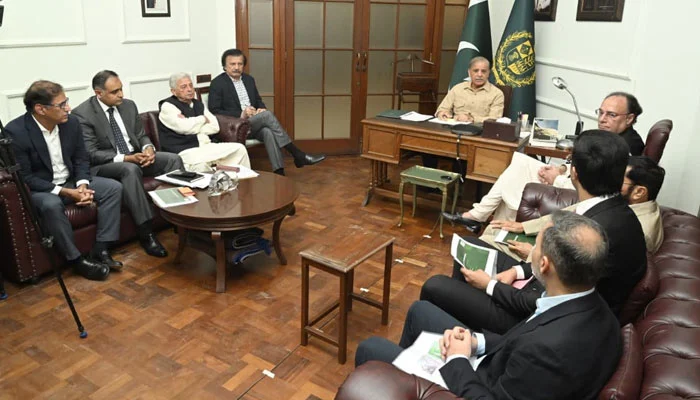
Prime Minister Shehbaz Sharif highlighted the Rs3 billion SME Risk Pool at a meeting of the Export Development Fund in Lahore on September 5, saying it would broaden access to export credit insurance and help businesses increase exports. Officials also told the meeting that the entire Rs24 billion currently available with the EDF had been allocated for investment aimed at facilitating businesses, while the fund was moving away from additional infrastructure expenditure toward research, skills and competitiveness initiatives.

The more consequential development, however, began several days before the prime minister’s meeting. On August 31, Pak EXIM signed two linked risk-sharing arrangements: the roughly Rs3 billion SME Risk Pool with EDF and a separate reinsurance agreement with the Islamic Corporation for the Insurance of Investment and Export Credit, or ICIEC, a member of the Islamic Development Bank Group. The government says the latter will bring international expertise in credit and political-risk mitigation while increasing Pak EXIM’s underwriting capacity.
Together, the arrangements create a more significant mechanism than the Rs3 billion headline suggests. The EDF pool is designed to improve SMEs’ access to Pak EXIM’s Trade and Export Credit Insurance against non-payment, giving smaller companies protection when extending credit to overseas buyers. The ICIEC arrangement, meanwhile, provides reinsurance support behind Pak EXIM, potentially increasing the institution’s ability to underwrite export risks across a broader portfolio.
That distinction matters for smaller exporters. A company entering a new foreign market can secure an order yet still face substantial exposure if a buyer defaults, becomes insolvent or payment is disrupted. Larger exporters are generally better positioned to absorb such losses or obtain financial protection; smaller firms have less room for a single unpaid overseas invoice. Export credit insurance is intended to transfer part of that risk, potentially allowing businesses to pursue customers and destinations they would otherwise consider too risky.
The government is positioning the mechanism within a broader attempt to change Pakistan’s growth model. Finance Minister Muhammad Aurangzeb said at the August 31 signing that Pakistan needed to move away from recurring growth cycles in which rising domestic activity fuels imports and eventually generates balance-of-payments pressure. He argued that sustainable expansion would instead require stronger private-sector-led exports and a substantially broader export base.
There is also a diversification problem behind that strategy. Aurangzeb said incremental gains around Pakistan’s existing roughly $30 billion goods-export base would not be sufficient, and called for expansion into new products, services, markets and exporter segments. He cited IT exports of around $4.6 billion and freelancer earnings of roughly $1.7 billion as areas already showing stronger performance, while stressing the need for broader gains in goods exports.
The new insurance architecture therefore targets a structural question: whether companies outside Pakistan’s established large-exporter base can be given enough financing and risk protection to participate more aggressively in international trade. The government says the Rs3 billion pool will specifically make insurance against non-payment more accessible to SMEs, while Pak EXIM’s reinsurance partnership is intended to strengthen the institution providing that protection.
Shehbaz also linked EDF reforms to Pakistan’s wider export strategy. Officials told his meeting that the fund’s leadership had been transferred to private-sector professionals and that work was under way concerning an extension of Pakistan’s GSP+ preferential trading status, which is important for continued preferential access to the European market.
But the ultimate test will not be the size of the announced fund or the number of agreements signed. The Finance Ministry itself acknowledged that success must eventually be measured by implementation — including whether the new arrangements generate additional financing capacity, stronger protection, new exporters, entry into new markets and ultimately additional exports.
That makes the Rs3 billion pool less important as a standalone government allocation than as one component of an emerging system. Pakistan is effectively attempting to place domestic risk-sharing underneath SMEs and international reinsurance behind its export-credit institution — a two-layer structure intended to make taking a chance on a new overseas customer less dangerous for Pakistani businesses.